How Much Is My Naples Home Worth? Zestimates vs. Comps vs. Appraisals (2026)


The quick answer: an online estimate is a starting point, not a value. Zillow reports that its off-market Zestimates miss the eventual sale price by a median 7.01%; on the August 2026 Naples median of $575,000 that is a swing of roughly $40,000 in either direction. Real value in Collier County is set by recent closed comparables, adjusted by someone who has walked the property, and confirmed by what buyers actually paid last month: 94.8% of the last list price.
Every Naples owner has checked the number at least once. The trouble is that three different numbers are on offer — the online estimate, the Property Appraiser’s value, and the neighbor’s asking price — and none of them is what a buyer will pay. In August 2026 the median closed price across the Naples market was $575,000, down 1.7% from a year earlier, the average sale took 99 days to find its buyer, and sellers collected 94.8% of their final asking price. Inventory sits at 5.4 months of supply, down from 8.1 a year ago. Those four figures say more about what your home is worth this fall than any algorithm can.
Key Takeaways
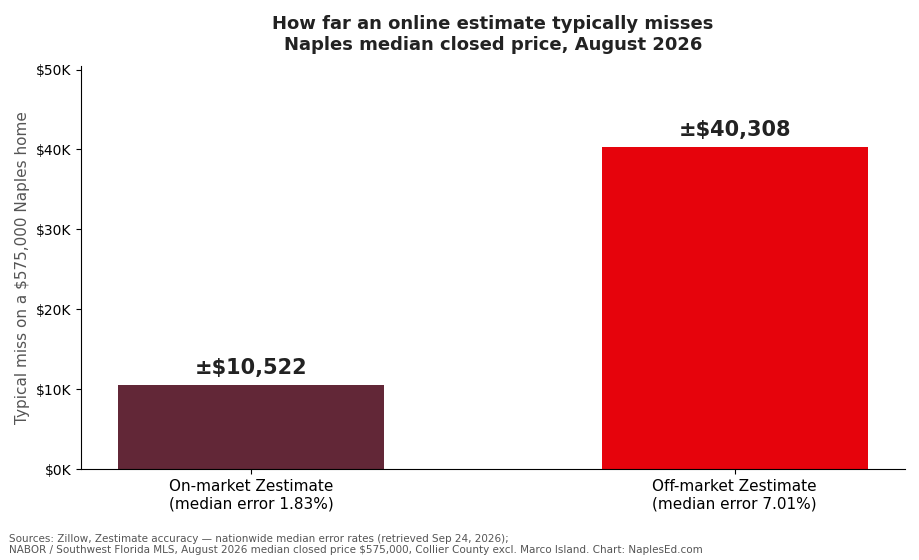
Zillow’s own accuracy page puts the median Zestimate error at 1.83% for homes already listed and 7.01% for homes that are not — the version every owner sees before listing is the less accurate one.
On the $575,000 August 2026 Naples median, a 7.01% median miss is about ±$40,300, and half of all estimates miss by more than the median.
The Collier County Property Appraiser’s value is set as of January 1 each year and, for homesteaded owners, the assessed value is capped at 3% or CPI growth — it lags the market by design.
A comparative market analysis uses closed sales, not asking prices; in July 2026 Naples sellers cut prices 970 times, so asking prices are a poor proxy for value.
The only number that settles the question is an accepted contract. Pricing from the data — comps, days on market, the list-to-sale ratio — gets you there faster than pricing from hope.
Data and sources current as of September 24, 2026. Market figures are the NABOR/Southwest Florida MLS August 2026 release for the Overall Naples Market (Collier County excluding Marco Island) unless noted.
Why the Number on Zillow Isn’t Your Price
Automated valuation models are good at one thing: homes that look like their neighbors. They take recorded sales, tax data, square footage and listing photos, then fit a curve. Zillow is unusually candid about the limits. Its accuracy page reports a nationwide median error of 1.83% for on-market homes and 7.01% for off-market homes. The gap is not an accident. Once a home is listed, the model can see the asking price and the photos, and it leans on both. Before listing, it is guessing at the things that decide value in Naples: whether the kitchen was redone in 2019 or 1999, whether the lanai faces the lake or the parking lot, whether the golf membership is mandatory, and whether the flood zone is X or AE.
Put the off-market error on the local median and you get the chart below. Half of all off-market estimates land within about $40,300 of the sale price on a $575,000 home. The other half miss by more. That is the number owners are quoting to each other at the mailbox.
Three Numbers That Are Not Your Market Value
Sellers usually arrive with one of these three numbers in hand. Each measures something real; none of them measures what a buyer will pay in the next 90 days.
Number | What it actually measures | Why it misleads a seller |
|---|---|---|
Zestimate or other online estimate | A statistical fit of public records and recent sales for similar-looking homes | Median error of 7.01% before listing (Zillow). It cannot see condition, view, membership status, insurance cost, or flood zone. |
Property Appraiser “just value” | The county’s estimate of value as of January 1 for tax purposes (Florida Statutes §192.042) | It is at least nine months old by the fall, and homesteaded assessed values are capped at 3% or CPI growth per year (Save Our Homes), so long-term owners see a number far below market. |
Neighbor’s asking price | What one seller hopes to get | Naples sellers received 94.8% of their final list price in August 2026, and July 2026 recorded 970 price reductions. Asking is not getting. |
The Property Appraiser’s number deserves a special word because it causes the most confusion. Under Florida law real property is assessed as of January 1 each year, and the Save Our Homes cap limits the annual increase in a homesteaded property’s assessed value to 3% or the change in the Consumer Price Index, whichever is lower. An owner who bought in 2012 can have an assessed value that is a fraction of today’s market value and a “just value” that is still a year behind. Neither is a pricing tool.
How a Comparative Market Analysis Actually Works
A comparative market analysis starts where the algorithm stops. The raw material is the same — closed sales — but the selection and the adjustments are done by a person who knows why two homes on the same street sold $90,000 apart.
The comps that count are closed sales from the last three to six months in the same community and the same product type: a Pelican Bay high-rise against Pelican Bay high-rises, a Lely Resort villa against Lely villas, not against the single-family side of the same gate. Each comp is then adjusted for what makes it different from your home: living area, lot and water or golf view, year built and renovation, pool and lanai, garage count, and for condos the floor and the elevator. Pending sales and active listings come in last, not as value but as the competition your listing will face on day one.
Two market-wide figures shape every adjustment this fall. The average sale in August 2026 took 99 days to go under contract, and supply has tightened to 5.4 months from 8.1 a year earlier. Fewer competing listings help a well-priced home; they do nothing for an overpriced one, because the buyer who passes on it has other choices. Cash also matters here: Florida Realtors’ SunStats shows 55.2% of Collier County closings in August 2026 were all-cash (that county figure includes Marco Island). Cash buyers skip the appraisal, but they price hard, and a cash offer is the cleanest read on value you will get.
Where the Appraisal Fits
When the buyer finances, the lender orders an appraisal, and that report becomes the third opinion in the deal. The appraiser works from closed comps the same way a good CMA does, but with a narrower lens and a later date — usually two to four weeks after you have already agreed on price. With the 30-year fixed rate at 6.95% in the week ending September 17, 2026, financed buyers are budget-bound, and an appraisal that comes in under contract forces one of three outcomes: the buyer brings cash, the seller cuts, or the contract dies. Pricing from real comps at the start is how you avoid the appraisal becoming the negotiation.
A Pricing Plan Beats a Price Guess
The practical use of all this is a plan, not a single number. The comps give a range. The competitive set — what is active and pending in your community right now — tells you where in that range to enter. The first two weeks on the market tell you whether the market agrees: showings without offers means the price is close; no showings means the number is wrong. In a market where sellers netted 94.8% of their last asking price, an entry price 8–10% above the comps does not buy negotiating room; it buys a price reduction and the stigma that comes with it.
If you want a firm number in days rather than months, a competing cash-offer process produces one — real buyers, real money, no algorithm. If you want the full retail result, my 1% listing service starts with a written CMA and a pricing plan before the sign goes in the ground. Either way, read the cost-to-sell guide first so the net, not the gross, is the number you are pricing toward, and the spring 2026 price-realism guide for what happens to listings that ignore the data.
Ed’s Take: What I’m Seeing in the Field
After enough listing appointments you learn that the owner already has a number before you sit down, and it is almost always the off-market Zestimate rounded up. Zillow’s own page says that number is the less reliable of its two, and the reason is not mysterious: it cannot see the 2008 roof or the lake view. What the August data tells me is that the Naples market is rewarding accuracy again. Supply has dropped from 8.1 months to 5.4, but sellers are still collecting 94.8% of list, which means buyers are paying for well-priced homes and walking past the rest. The 99-day average is not a warning label; it is the cost of a bad first price. My prediction: through the 2027 season, the gap between accurately priced and aspirationally priced homes widens — the first group sells in the first month, the second group becomes next spring’s price reductions.
Final Thoughts
Your home is worth what a buyer will pay in the next 90 days, and the evidence for that number already exists in the closed sales around you. Use the online estimate as a conversation starter, use the Property Appraiser’s value for your tax bill, and use a CMA, the days-on-market data, and the list-to-sale ratio to set the price. The market will tell you quickly whether you got it right. Listen in the first two weeks.
Frequently Asked Questions About Naples Home Values
How accurate is a Zestimate for a Naples home?
Zillow reports a nationwide median error of 1.83% for on-market homes and 7.01% for off-market homes. On the August 2026 Naples median of $575,000, the off-market figure is a typical miss of about $40,300, and half of all estimates miss by more than that. Naples-specific factors — views, golf memberships, flood zones, insurance — are exactly the inputs the model cannot see.
Is the Property Appraiser’s value my home’s market value?
No. Florida assesses real property as of January 1 each year, so the number is months old, and homesteaded assessed values are capped at 3% or CPI growth under Save Our Homes. It is a tax figure, not a pricing figure.
What is a comparative market analysis?
A CMA is a valuation built from recent closed sales of similar homes in the same community, adjusted for differences in size, view, condition, and features, with pending and active listings used to gauge competition. It is the method a listing agent and an appraiser both use; the difference is the agent does it before you price, the appraiser after.
How long does it take to sell a home in Naples right now?
In August 2026 the average sale in the Overall Naples Market took 99 days from listing to contract, 7.5% faster than a year earlier, with 5.4 months of supply. Well-priced homes go faster than the average; overpriced ones are the reason the average is 99.
Can I get a real offer without listing?
Yes. A competing cash-offer process brings multiple written cash offers on a specific home, which is a harder number than any estimate. Cash represented 55.2% of Collier County closings in August 2026, so the buyer pool is real. Compare that number against a full-service listing before choosing.
Article By: Ed DiMarco MS, MA
Ed DiMarco is a Naples, Florida real estate agent with Realty Hub — 14 years as a Gulf Coast, Florida real estate agent, $54 million in closed transaction volume between March 2025 and September 2026, 36 closed sales on Zillow with a 5.0★ rating, and quotes in Kiplinger, USA Today, Bisnow and Yahoo News. He lists Naples, Bonita Springs, Estero and Marco Island homes for a 1% listing fee with full service and represents buyers with part of the commission credited back at closing. MS in Business Management and MA in Communication, University of South Florida. Investor since 2004.